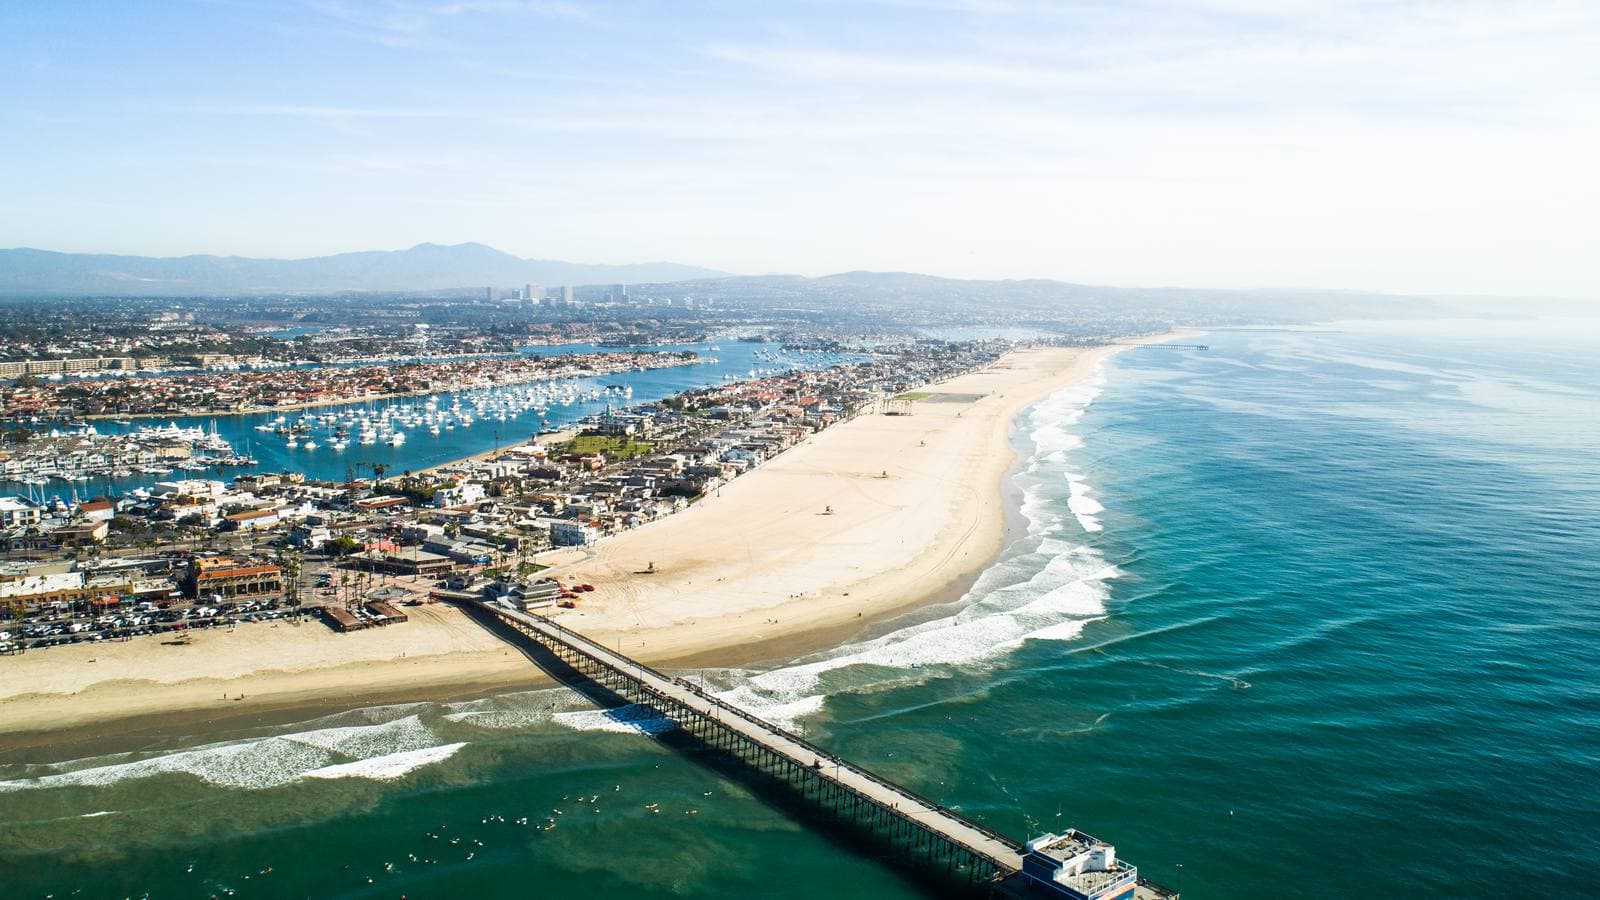
Is a waterfront home in Newport Beach worth what you think it is? When the property sits on the ocean, harbor, bay, or a canal, the value depends on more than square footage and finishes. Views, dock rights, seawalls, permits, and flood risk can move numbers in a big way. In this guide, you'll learn how waterfront appraisals work here, what local factors matter most, and how to prepare so your value is supported. Let's dive in.
Why waterfront appraisals are different
Waterfront property is not one-size-fits-all in Newport Beach. Oceanfront along the open Pacific, harbor-front on Balboa, bay and Back Bay views, and canal properties each offer different amenities and risk profiles. True like-for-like comparable sales are scarce, which means appraisers rely more on local nuance and well-documented adjustments.
Regulations and environmental factors also play a larger role. Permits for docks and seawalls, flood zone designations, and long-term shoreline conditions can influence both lender risk and buyer demand. In this market, small differences in water access, view, and compliance can translate to large differences in value.
How the appraisal process works
Here is the typical flow for a waterfront appraisal in Newport Beach:
- Engagement: A lender or private party orders the appraisal.
- Property inspection: The appraiser tours the exterior and interior, noting view lines, dock and boat facilities, seawall condition, site elevation, floodproofing, and any signs of water intrusion.
- Data collection: The appraiser reviews deed and permit history, surveys, elevation certificates, HOA documents, and any rental income records.
- Market research: The appraiser identifies recent comparable sales and active or pending listings in the most relevant submarket.
- Valuation: The appraiser applies the Sales Comparison Approach as primary, with the Cost and Income approaches as support where applicable.
- Report delivery: A written report goes to the ordering party with a reconciled opinion of value.
What drives value in Newport Beach
Waterfront type and access
Oceanfront typically carries a premium for open water views and beach access. Harbor and bay-front properties emphasize boating and protected water. Canal properties can offer intimate water settings but may have depth or navigability limits. Deep-water access and a private slip or pier usually add value compared with shallow or shared access.
Marine structures and permits
Seawalls, bulkheads, docks, and lifts matter. Their condition, construction type, and documented permits influence both lender acceptance and buyer confidence. An undocumented or deteriorated structure can trigger value reductions or lender conditions until it is repaired or clarified.
Elevation and flood risk
FEMA flood zone status and base flood elevation influence insurability, which affects holding costs and buyer pools. Elevation certificates, flood vents, and raised utilities can improve marketability. Over time, sea-level rise and erosion concerns have gained attention among buyers and lenders in coastal Orange County.
Legal rights and restrictions
Ownership or lease status of a dock or slip, recorded easements, and littoral or riparian rights shape what you can do with the property. Coastal development restrictions may limit expansion or rebuilds after damage. Clear documentation reduces uncertainty and supports value.
Market dynamics and finishes
At the high end, sample sizes are small and tastes vary. Custom finishes, modern systems, and curated outdoor spaces carry weight. With fewer comps, appraisers may include more narrative, pair sales carefully, and lean on secondary approaches to support a final opinion.
The three valuation approaches
Sales Comparison Approach (primary)
For single-family waterfront homes, the Sales Comparison Approach is typically primary. The appraiser selects the closest matches for water orientation, view quality, dock or slip ownership, lot position, and improvement level. Adjustments account for differences in view, access, elevation, seawall condition, lot size, and permitted uses. In a constrained comp environment, the appraiser explains the rationale in detail.
Cost Approach (supporting)
When homes are new, highly unique, or comps are sparse, the Cost Approach helps. The appraiser estimates replacement cost of improvements, subtracts depreciation, and adds land value. It is useful for newer or substantially rebuilt properties, but still secondary to market evidence.
Income Approach (selective)
If a property produces rental income, the appraiser may apply a Gross Rent Multiplier or capitalize net operating income. In Newport Beach, short-term rental rules and data quality vary, so the Income Approach is used when documented income is relevant and reliable.
Common adjustments you may see
- View quality: full ocean or bay, partial, or oblique.
- Water access: private dock or slip ownership versus leased or association managed.
- Dock and seawall condition: newer, permitted structures support value; failed or undocumented structures reduce value.
- Depth and navigability: larger vessel capacity typically increases value.
- Elevation and mitigation: higher finished-floor elevations and floodproofed utilities can reduce risk and insurance costs.
- Lot size and shoreline change: documented accretion or erosion affects land value.
- Parking and access: constraints on the peninsula or narrow lots can reduce marketability.
How to prepare for the appraisal
Gather documents in advance
- Recent surveys, plot plans, and legal descriptions.
- Any available elevation certificate.
- Permit history for seawalls, docks, remodels, and additions.
- Maintenance and repair records for marine structures.
- HOA documents, slip agreements, or marina leases.
- If applicable, rental income statements and short-term rental history.
- Photos that clearly show view corridors and shoreline features.
Having these ready helps the appraiser verify key details and reduces re-inspection requests.
Address known pain points
- Seawalls and docks: If you know of issues, obtain an engineer's report or repair plan and pull relevant permits. Clear documentation limits value deductions and lender concerns.
- Limited comps: Provide thoughtfully selected sales with notes on why they are comparable. The appraiser will still weigh market evidence independently.
- Flood and elevation: Share elevation certificates and any mitigation measures. Clarity on insurability can influence marketability.
- Slip status: Clearly show whether the slip is owned, leased, or association managed, and provide any terms.
Set realistic expectations
Waterfront appraisals often take longer and cost more due to complexity. You may see more narrative and detailed explanations of adjustments, especially when high-end comps are scarce. Build in time for follow-up questions.
Regulations and insurance to check
Flood and coastal rules shape lending and buyer decisions. The following resources offer official context:
- Review your property's flood zone on the FEMA Flood Map Service Center. These maps inform insurance requirements and lender guidelines.
- For coastal permits and shoreline armoring policies, consult the California Coastal Commission. Permit history and compliance can affect value and insurability.
- To verify local permits for docks, piers, and seawalls, visit the City of Newport Beach. The planning and harbor departments maintain relevant records.
- For tidal datums and water-level information, reference NOAA Tides and Currents. Tidal context can inform navigability and dock utility.
If the appraisal comes in low
A low appraisal is not the end of the road. You can provide additional documentation or relevant comps and request a reconsideration of value. Depending on the lender and contract terms, you might also renegotiate price or terms, or choose to walk away.
Work with a local advisor
In Newport Beach, the details around docks, flood zones, and coastal permits matter as much as the finishes inside the home. You want a trusted partner who can anticipate lender questions, gather the right documents, and frame the property's unique value clearly for the appraiser. With deep local market knowledge and hands-on transaction management, you can move from uncertainty to confidence.
FAQs
What affects Newport Beach waterfront value most?
View quality, water access and depth, the condition and permits for docks and seawalls, site elevation and flood risk, and legal rights such as slip ownership typically carry the most weight.
How does flood zone status impact an appraisal?
Flood zones do not automatically reduce value, but higher risk can increase insurance costs and narrow the buyer pool, which may put downward pressure on market value.
Do private docks and slips always add value?
Yes, when owned and in good condition, they often add value, but the amount depends on capacity, depth, and local demand. Leased slips generally add less value than owned.
What documents should I provide before the appraisal?
Elevation certificates, permit histories, surveys, marine maintenance records, HOA and slip agreements, relevant photos, and any rental income documentation help the appraiser verify key factors.
How are unique or newly built waterfront homes valued?
The Sales Comparison Approach remains primary, supported by the Cost Approach to estimate replacement cost and by the Income Approach if reliable rental income is available.
What if the seawall or dock needs repair?
Expect an adjustment for condition or a lender requirement for repair. Providing engineer reports, permits, and bids can limit uncertainty and clarify value impacts.
← Back to the Blog